Overview of Real Estate in Panama
Today, we explore a common concern, particularly for North American investors: the possibility of obtaining a US mortgage for Panama property. Our research and expertise have shown us that obtaining a mortgage is more challenging for foreigners, yet not impossible. If you don’t have Panamanian residency yet, you can choose between a bank loan and developer financing.
In this case, expect to pay higher rates ranging between 7% and 9%, and be ready to collect documents such as the last 2 years of returns, a credit report from your home country, bank statements dating back one to two years, and a life insurance policy covering the whole amount of the loan.
We will touch upon types of mortgages and whether they can help us obtain a unit that will be suitable for Qualified Investor. Since foreigners are getting more and more interested in the country of the canal, and since the market looks promising in 2026, this has become an interesting topic for the international investor.
Types of Mortgages Available in Panama
As we've recently published in one of our articles, there are different ways to buy property. There are only two mortgages, per se. The other two options entail financing, which technically is not the same thing. Yet for the sake of clarity, we'll put them all under “types of mortgages”.
Typical bank mortgage
Like in any country, in Panama, you can buy a home through a bank loan. This means that you pay only a percentage of the property (down payment) and the bank takes care of the rest. You will then be charged monthly installments with interest through a stipulated period.
Government-backed mortgage
Some governments support mortgages by insuring and guaranteeing the loan, which results in lower interest rates and easier accessibility. The downside is that these are not always available, and they are rarely available for foreigners.
Seller’s financing
The seller may agree to finance the whole amount or part of the overall cost. This is a more flexible solution and usually entails lower interest rates.
| HELOC | Bank loan | Developer financing | |
| Essence | Revolving line of credit secured by a property | Money borrowed from the bank and to be paid with interest in a stipulated timeframe | Agreement done with a real estate developer to pay through an initial down payment and subsequent installments |
Best for | Buyers who already have a property | Buyers who seek long-term financing | Buyers who seek a cost-effective approach to real estate |
Interest rates in general | Variable | Fixed or variable | Depending on the project’s phase (increasing as construction develops) |
Interest rates (confirm with each provider) | 7% (depending on the bank) | 7.50% – 8.50% (depending on the bank) | Based on interest rate of the market plus 1 percent (depending on the developer) |
Approval | Fast once the credit line has been established | Requires extensive paperwork | Usually fast and flexible process |
Main advantages | Interest is paid only on the borrowed amount | Longer repayment terms, fixed payments | Lower costs of real estate and easier approval |
Main disadvantages | The house itself is collateral | Stricter requirements, the property itself is collateral | Risk of construction delays or failure to deliver |
Disclaimer: the information in the chart above was taken from available sources at the time and may vary over time and across providers. For up-to-date information, consult with the banks or developers.
Developer’s financing
Similar to the above, there is such a thing as developer financing. This is a win-win deal in which the buyer, by depositing down payments and installments during construction, helps fund the project.
When construction goes according to schedule, this is the ideal solution: you can use rental income to pay for the loan.
Mortgage Terms and Conditions
Last year, the loan portfolio of the International Banking Center grew by 5.91% according to the Superintendency of Banks, which shows the healthy loan system currently operating in the country.
We have information about bank interest rates from last year, which may be useful for a general view. For foreigners, the rates and conditions are higher, with a down payment from 30% to 40% and interest from 6.5% to 9.5%.
Requirements for Obtaining a Mortgage
Requirements for Nationals
- National ID (cédula)
- Utility bill as proof of address
- Credit report to show a reliable credit history
- Proof of income showing employment and recent payments
- Tax returns if the person is self-employed
- Bank statements for the last 6 to 12 months
- Life insurance that covers the whole loan amount in case of death
Requirements for Foreigners
- Passport and second ID with a picture
- Utility bill as proof of address
- Credit report from the home country
- Resume
- Last two years of tax returns
- Bank statements dating back one to two years
- Letter of employment
- Audited financial statements if the individual is self-employed
- A life insurance policy that covers the whole amount of the loan in case of death
- Down payment between 20% and 40%
As we can see from the lists above, foreigners face stricter requirements. So, if you are applying for a loan as a foreigner, expect to navigate longer waiting times and more red tape. Things become much easier when you become a Panama resident through any of the available visa programs.
Disclaimer: the information published here about mortgages and real estate is provided for general knowledge; hence, this article does not constitute financial or legal advice. For updated information and information that concerns your case specifically, please contact the Mundo team or consult with a trusted advisor.
Process of Applying for a Mortgage
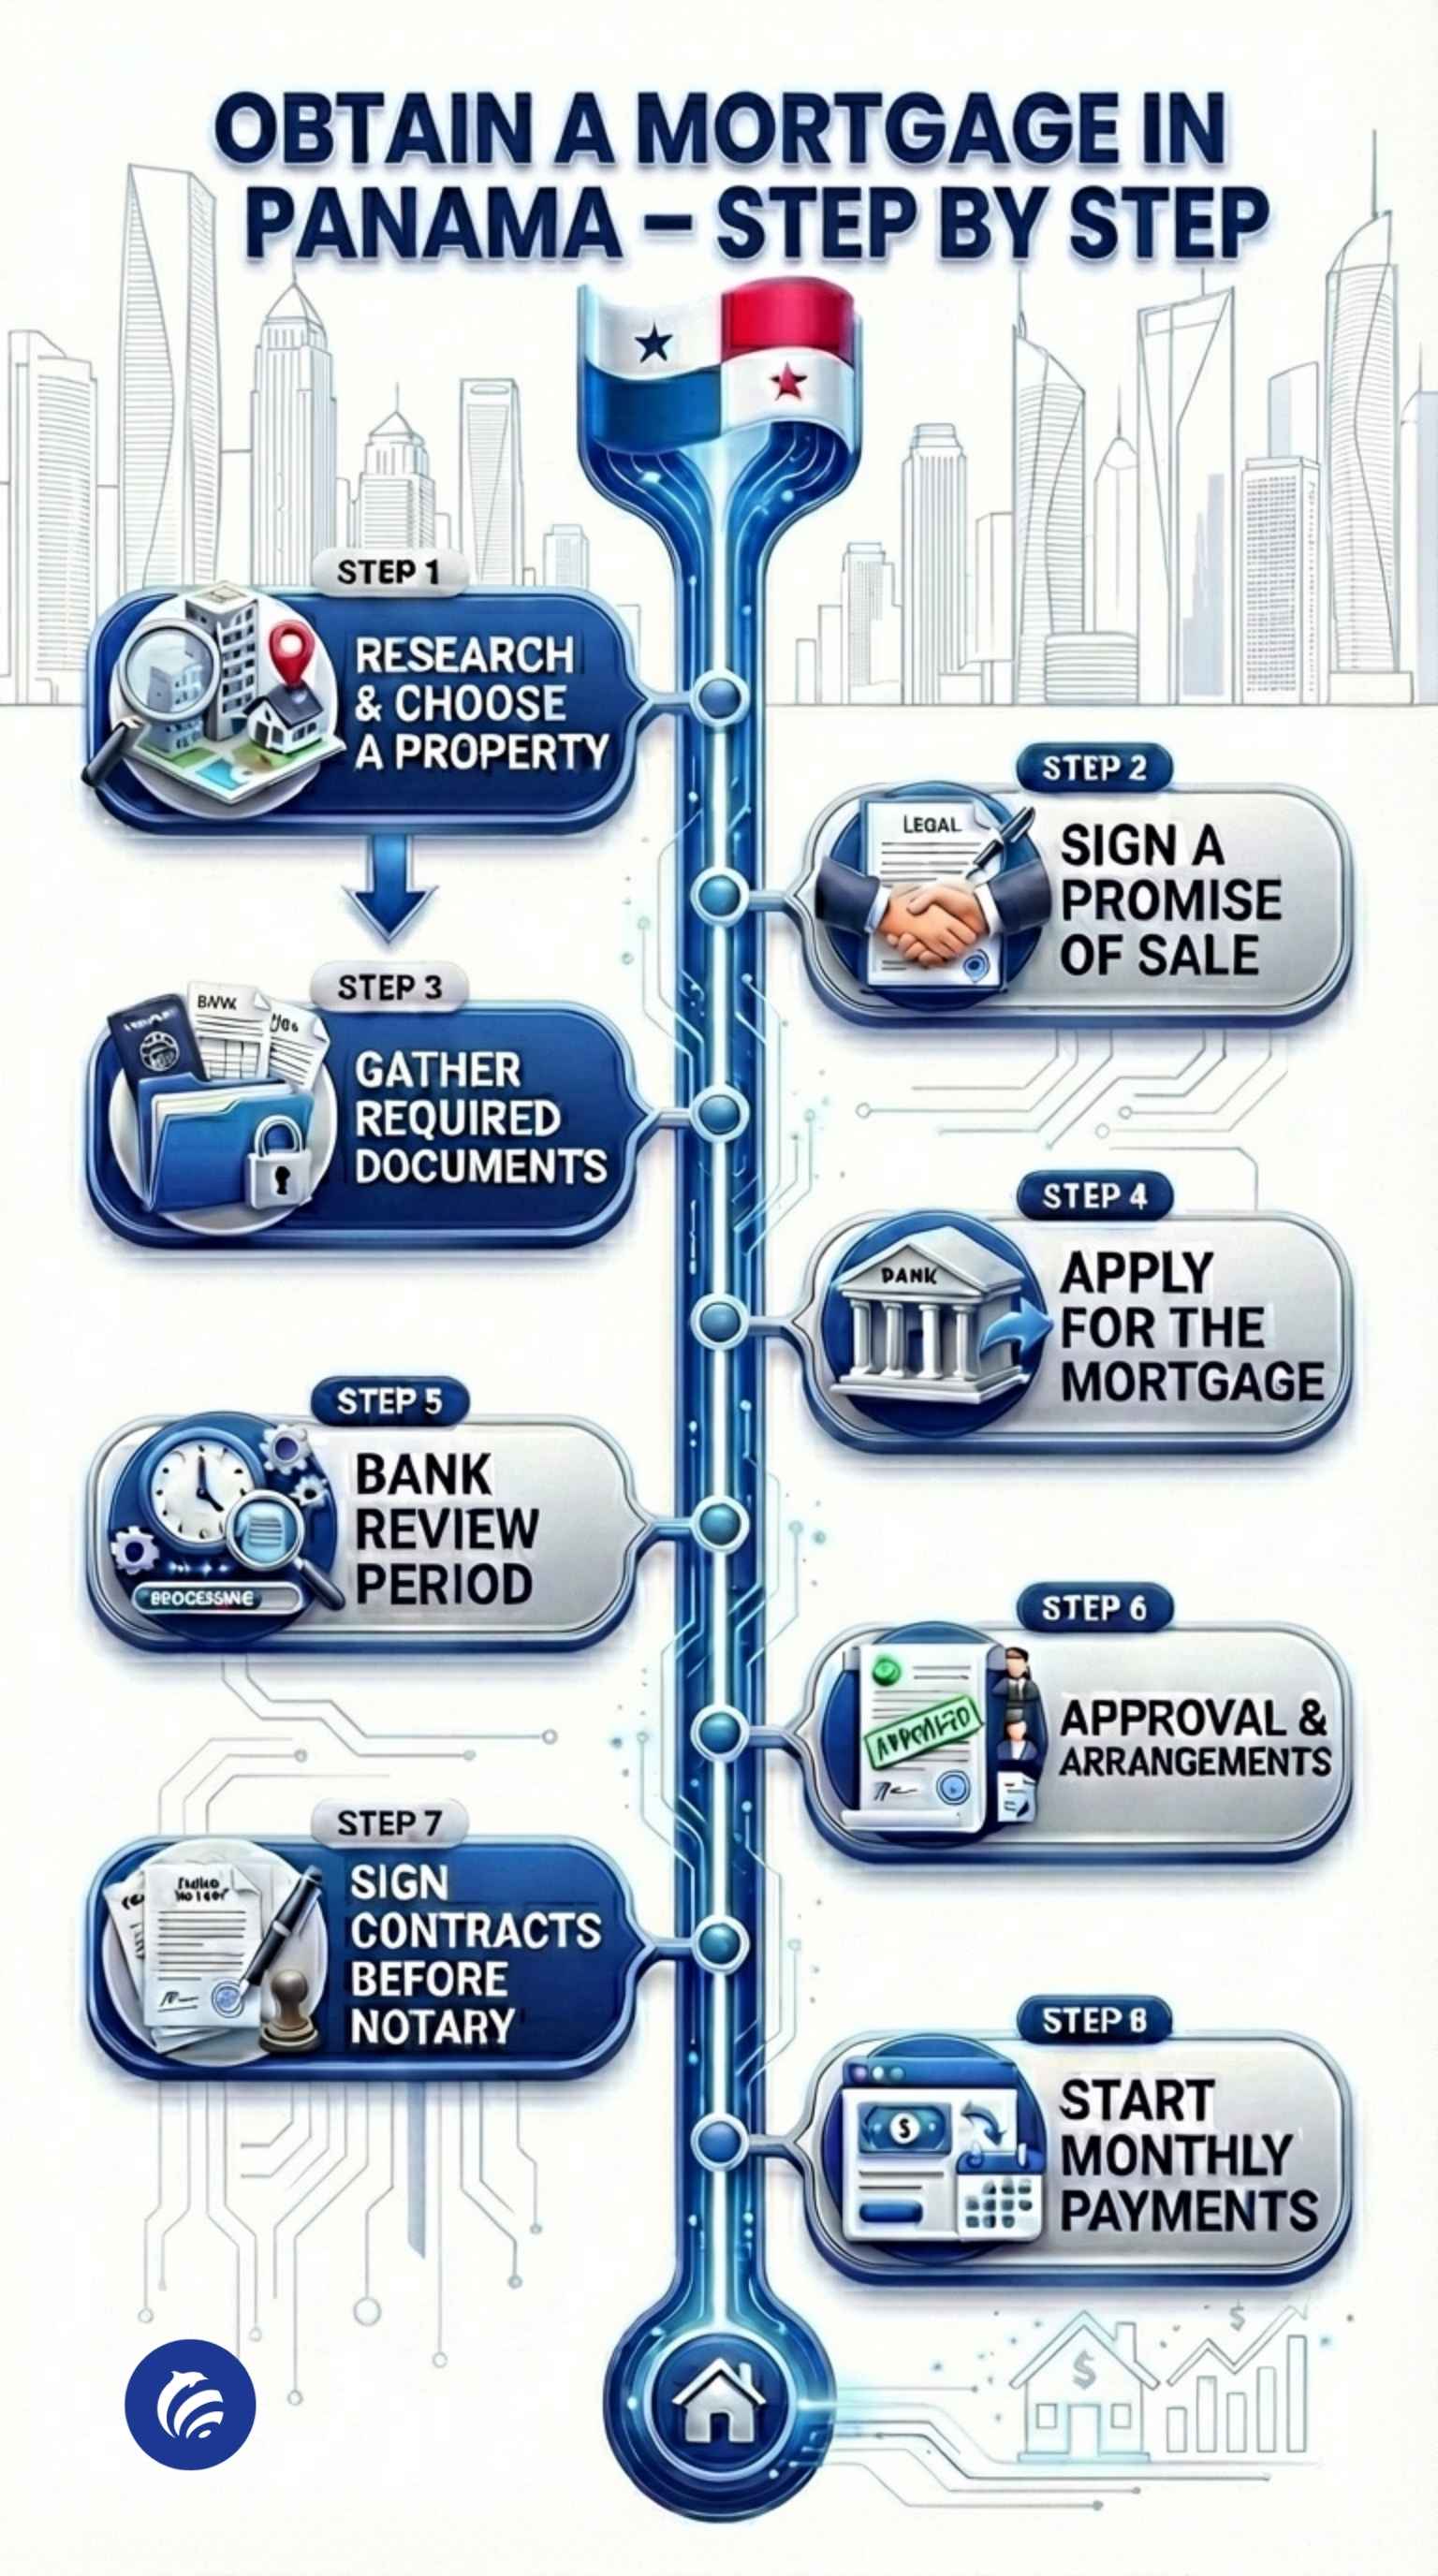
The process begins with choosing a property you like and an institution that will facilitate the loan. Then, the longest stage is focused on gathering all necessary documentation and waiting for the bank's resolution. Finally, it ends when you sign the property agreement before a public notary, and the bank makes the payment on your behalf.
Costs and Fees Associated with Mortgages
We can see a clear difference between Panamanians/residents and foreigners. If you are from the US and don't have residency, expect to pay interest rates from 7% to 9%, while for locals, they vary between 4.5% and 7%.
Downpayments are larger for US and Canadian citizens, starting at 30% and reaching 50% on occasion. Residents, on the other hand, are required to make downpayments of 10% to 20%.
Visit our featured article for a comparison of different Panamanian banks showing interest rates, minimum down payments, and estimated monthly payments based on the most current data available at the time of writing.
Tax Implications of Owning Property in Panama
Owning real estate in Panama comes with tax implications. All taxpayers will pay less for their primary residence and more for other units/apartments/houses that they may have.
Buyer Taxes in Panama
We have prepared the following table to help us grasp the tax implications on owning real estate.
Property value | Tax rates on Primary residence | Tax rates on other real estate |
Up to $120,000 | Exempt | According to tiers |
From 120,001 to 700,000 | 0.5% | According to tiers |
From 700,001 | 0.7% | According to tiers |
Up to 30,000 | Exempt | Exempt |
From 30,001 to 250,000 | According to tiers | 0.6% |
From 250,001 to 500,000 | According to tiers | 0.8% |
From 500,000 | According to tiers | 1% |
Note: This table shows general information about tax rates, yet it doesn't include case-by-case considerations, exemptions, reliefs, or treaties. The owners may also be liable to taxation in their home country or in other countries where they may have tax residency. The tax rates published in this table may be outdated at the time of reading. Please consult with a certified professional.
Foreign Ownership and Rights
Can Foreigners Buy Property in Panama?
Mundo’s experts consider this to be one of Panama’s best advantages: foreigners have exactly the same rights as Panamanians. The only exception is in areas within 10 kilometers of any international border, in which case, foreign ownership is forbidden. There's also another restriction that involves coastal land.
Real estate within a close range of the coast is government-owned and can only be sold through concession. However, this goes for both expats and citizens/residents.
Ownership Rights for US Citizens
U.S. citizens have the same rights as any foreigner.
Financing Options for US Citizens
Mortgage Availability for US Citizens
Using a loan from a foreign bank in Panama is not a usual practice. Although there can be agencies that facilitate this, the most traditional path for Canadian and US citizens is through a Panamanian bank.
A common strategy is to obtain a HELOC (Home Equity Line of Credit). These are common both in Canada and the US, and also in the United Kingdom.
Although HELOC is not officially a second mortgage (because it has more flexible terms), the collateral is the borrower's property. Even so, they enjoy more popularity than second mortgages, which are seen as sterner and associated with an undesirable level of debt.
Down Payment Requirements
U.S. citizens are under the same requirements as any foreigner, having to pay down payments varying from 30% to 40% or 50% (see above).
Interest Rates for US Citizens
Interest rates for U.S. citizens are the same as for any foreigner (please see the section above).
Interaction of US Taxes with Property Ownership in Panama
IRS Declaration Requirements
U.S. citizens are obliged to declare their Panama apartments, lands, condos, and any other assets to the IRS. This applies whether they are living in Panama or the United States.
Double Taxation Concerns
Our experts encourage readers to consult with certified experts because there may be treaties or reliefs to avoid double taxation.
FATCA Reporting Obligations
Inexperienced buyers often mix up the different types of tax. All citizens from the United States are obliged under FATCA; however, this involves banking and not necessarily real estate. In simple words, if they open an account abroad, they should file a FATCA report regardless of whether they buy real estate or not.
Panama residency goes hand in hand with real estate
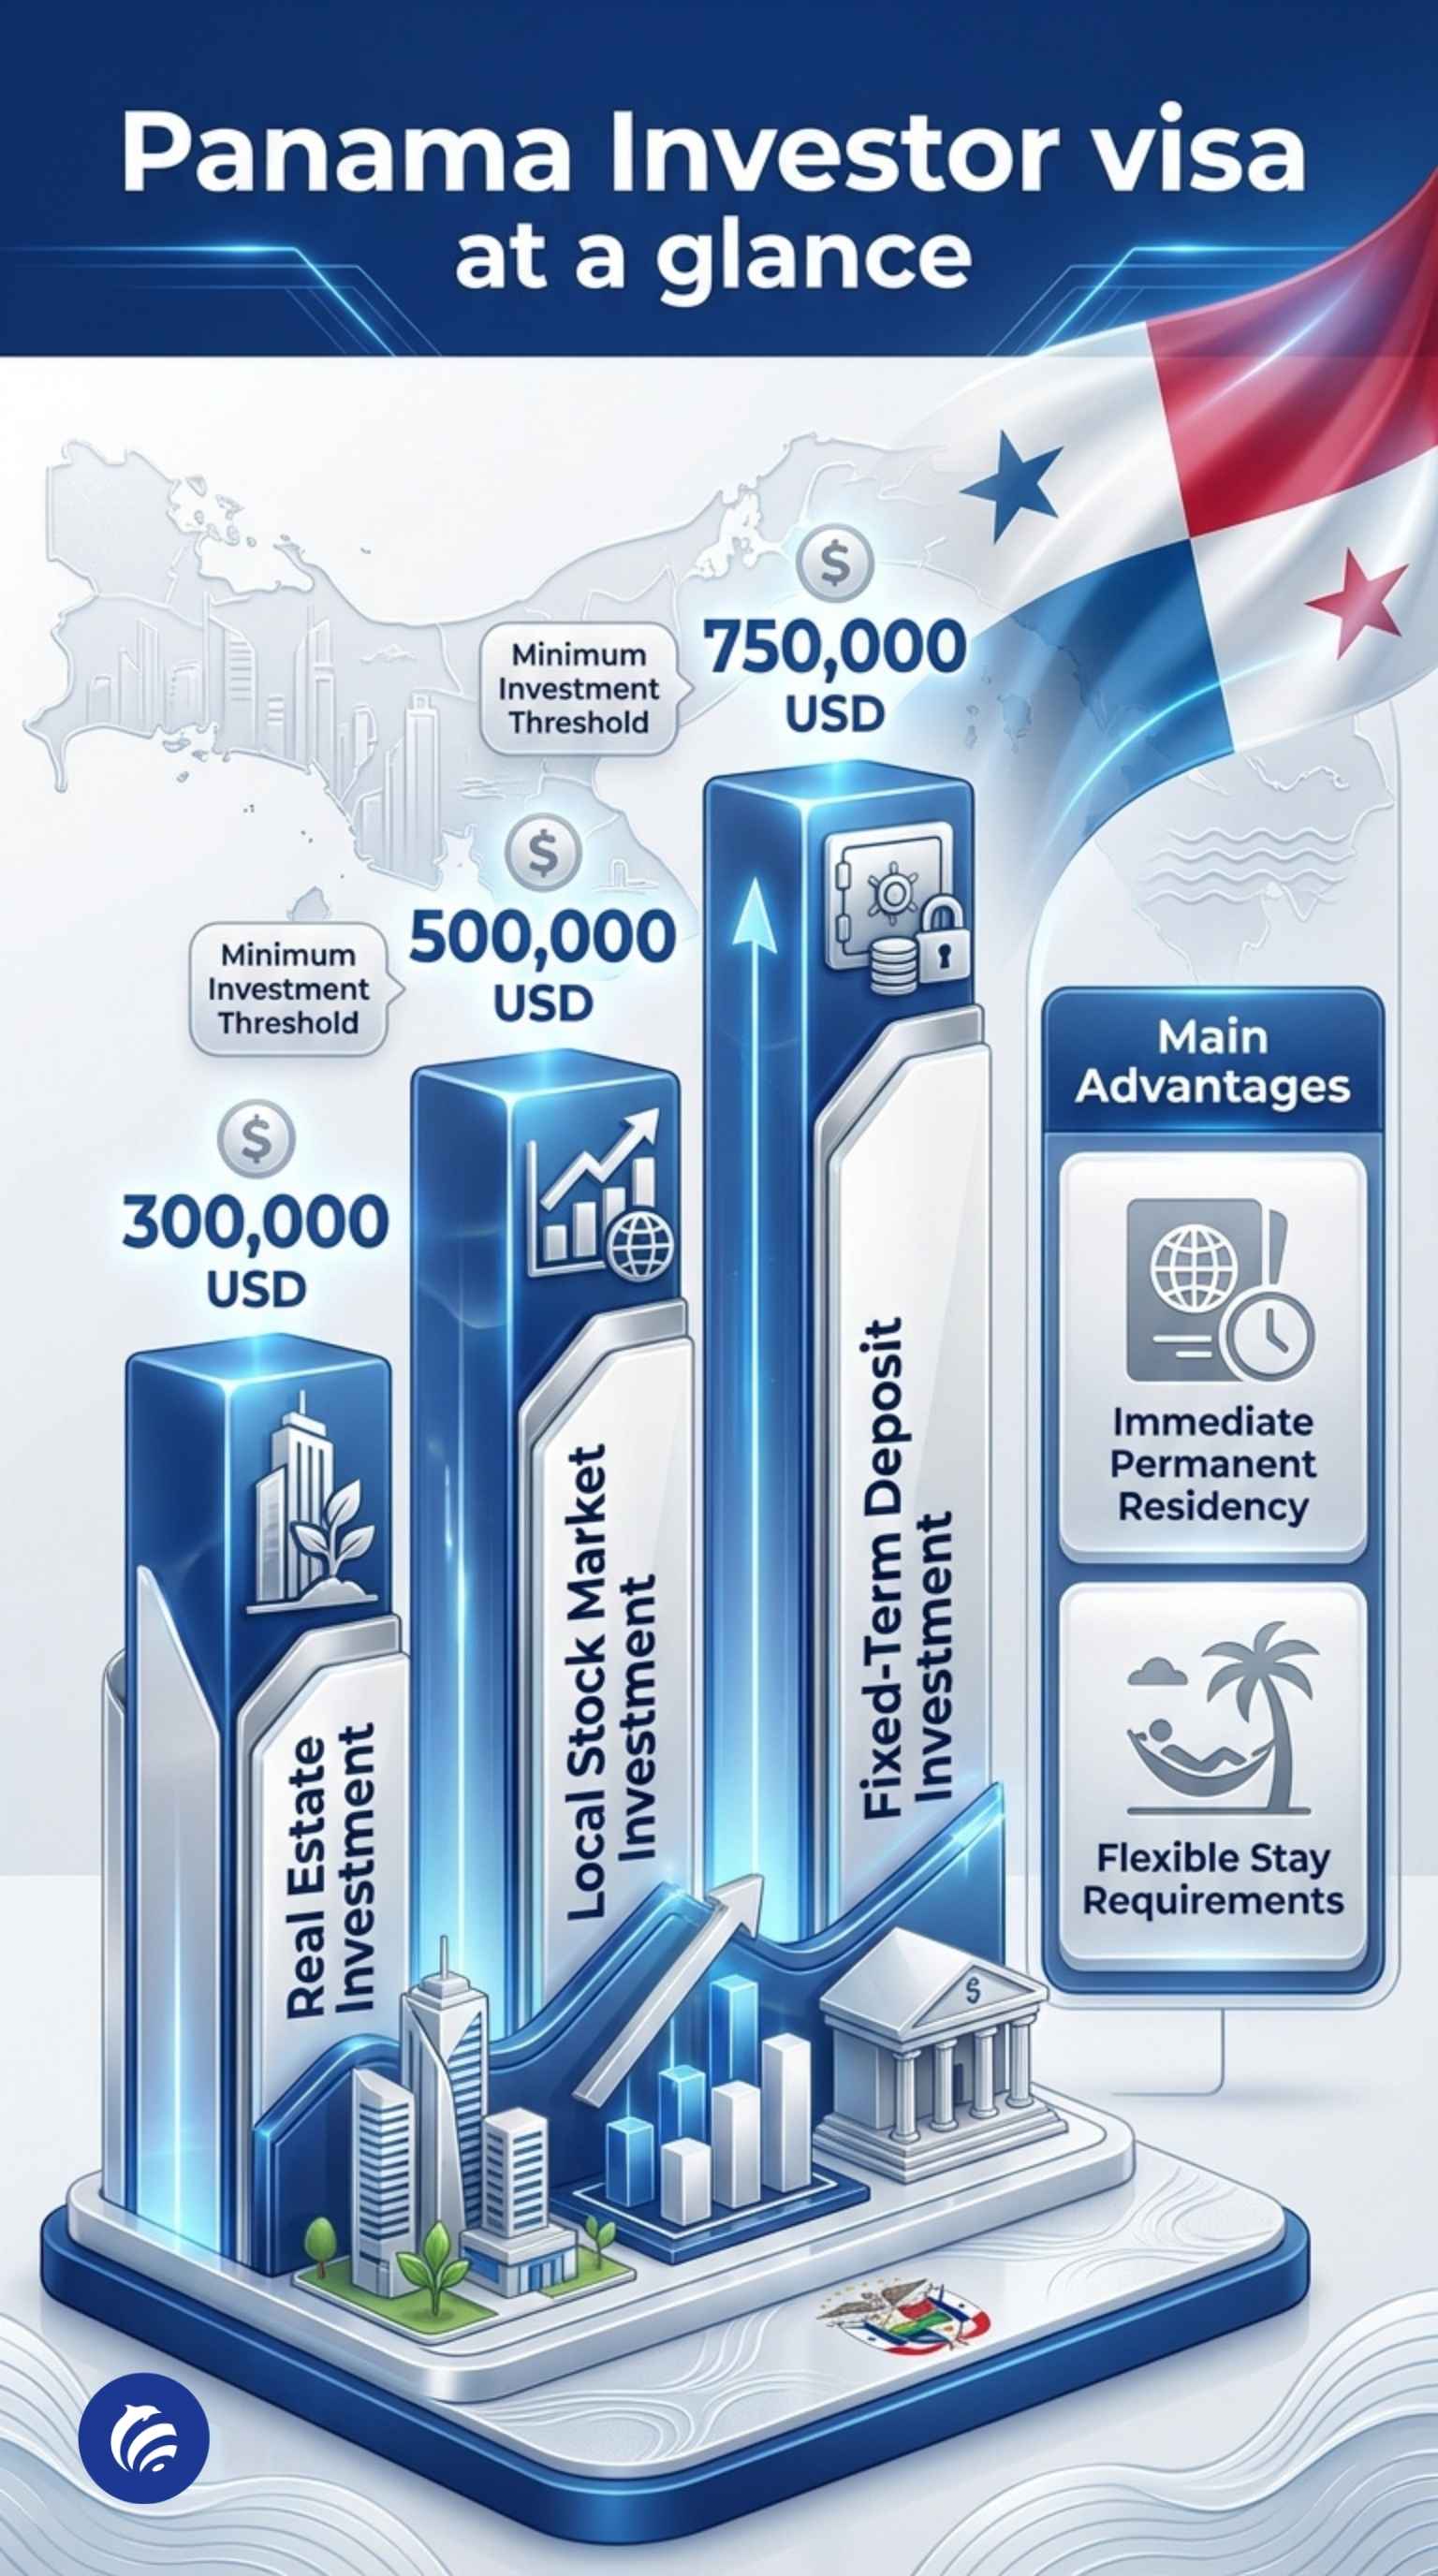
It's possible to access Panama residency by real estate through several programs. The most popular and accessible alternative is Qualified Investor. The reason is simple: it is a straight route to immediate permanent residency at a convenient investment. For this investment, the applicant can get premium units in the best areas.
The visa is flexible in terms of minimum stays, and it allows you to sell the property after a stipulated time.
There are two other visas with real estate within their requirements. Friendly nations is open to citizens from friendly countries (which include the US and Canada). It requires demonstrating financial ties to Panama, and a way to do this is through purchasing real estate.
Finally, the pensionado visa allows you to reduce the minimum pension income (from 1,000 a month to 750 a month) for a real estate investment of 100,000.
Contact Us for More Information
We are a publication dedicated to financial freedom and a team of advisors, lawyers, and agents who, with different partners, provide related services.
We specialize in helping foreigners achieve their goals in the country of the canal, buying real estate, incorporating companies, establishing foundations, or opening bank accounts.
We also reach other jurisdictions like Sao Tome, Vanuatu, and the Caribbean, and several others where it's possible to open bank accounts or incorporate entities. Contact us now regarding the service of your interest.